Published on 30 October 2026
How to integrate Ukraine into the European Union without sacrificing French beet and oilseeds? These two sectors, alongside wheat and corn, are among the first that Ukraine's agricultural power could endanger. Ukraine produces beet at costs significantly lower than those in France, and it already ships as much oilseeds to the European Union each year as France harvests.
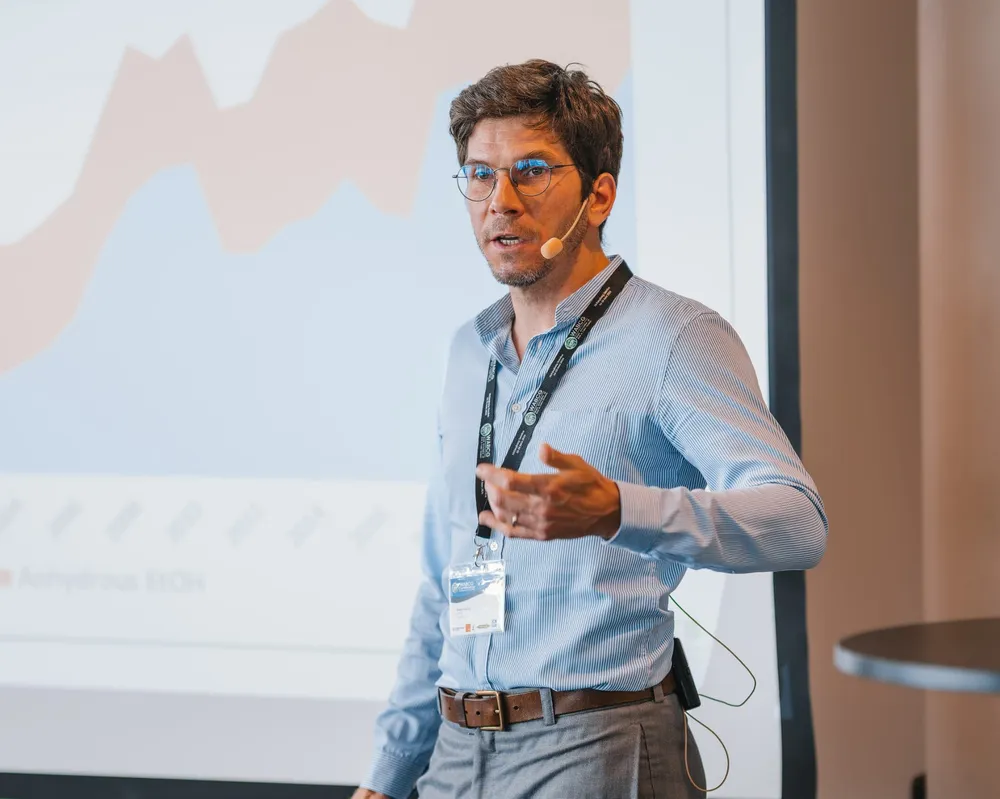
At the Agridées back-to-school conference at the end of September, representatives from both sectors attempted to answer this question: Benjamin Lammert, president of the French Federation of Oilseed and Protein Producers (FOP) and of the interprofessional organization Terres Univia, and Alexis Patry, director of the ARTB, the economic institute of the beet sector. Their diagnosis is the same. Their answers too.
An impossible gap to bridge
In beet, Ukraine produces at costs "around 30% lower than France," according to Alexis Patry, whom we interviewed after the conference (read our interview: " Can we save French beet? "). Between its agroholdings and the largest French farms, the size ratio ranges from 1 to 1,000. Believing that the two can coexist is, according to him, an illusion: the less competitive will disappear, and the movement has already begun. Even alignment with European standards will not be enough to bridge the gap, due to the lack of comparable farming structures.
"The one who sets the price is the one who is the most competitive." Benjamin Lammert
Benjamin Lammert presents the same orders of magnitude. Ukraine cultivates about 30 million hectares of arable land, nearly three times that of France and one-third of the European Union. The top ten Ukrainian agroholdings manage 2.8 million hectares, equivalent to the area of 22,000 French producers. "Ten farms represent a quarter of French producers," emphasizes Benjamin Lammert. Echoing the term "cost hunters" used by Olivier Antoine in our columns, he adds: "The one who sets the price is the one who is the most competitive."
Sectors built on a price level
The risk is not only about volumes but also about their effects on prices. Both sectors have restructured to operate at a certain market level, in other words, based on prices that allow them to remain profitable. On the sugar side, the end of European quotas in 2017, which intensified competition and pressure on prices, resulted in the closure of about twenty factories in nine years in Europe. If prices were to plunge sustainably, due to an influx of production capable of increasing very sharply from one year to the next, "all the production that has restructured in our European areas would not be able to survive," warns Alexis Patry. This would lead to new factory closures and weakened territories.
On the oilseed side, the sector has been built without any customs protection: from the creation of the Common Agricultural Policy (CAP) in 1962, Europe accepted, at the request of the United States, to allow seeds to enter without tariffs. It had to invent its own outlets, such as biodiesel and non-GMO soy, which is paid €100 to €120 more per ton than GMO soy. It is these balances that a Ukrainian influx could disrupt. About seven million tons of Ukrainian oilseeds, including seeds, oils, and cakes, already arrive each year on the European market, equivalent to French production.
France on the front line
For sugar, France is particularly exposed. Together with Germany and Poland, it accounts for 75% of European beet production, and it supplies deficit countries like Italy, Spain, or Greece. Any influx, whether from Ukraine or Mercosur, would primarily hit these surplus areas. Alexis Patry warns against overly simplistic reasoning. The 180,000 tons of sugar expected from the Mercosur agreement indeed represent "the equivalent of a standard sugar factory. But the impact can be much greater. By removing, for example, 30,000 tons of sugar to be processed for six sugar factories (a total of 180,000 tons), this influx of sugar weakens the six factories in question (and not just one factory) and, of course, the beet growers who supply them."
"Directing all or part of the Ukrainian production towards certain outlets would help smooth out the supply-demand imbalances." Alexis Patry
Directing towards energy
Hence the joint proposal from both sectors: to reserve part of the Ukrainian supply for certain uses, foremost among them biofuels. "Directing all or part of the Ukrainian production towards certain outlets would help smooth out the supply-demand imbalances that may arise. It is a way of managing the market that seems relevant and flexible," explains Alexis Patry. For beet, this direction involves raising incorporation mandates, which would make room for a surplus converted into ethanol rather than sugar. In France, about 20% of the approximately 35 million tons of beets harvested each year already go to ethanol. A "win-win" solution, according to him: the sugar market would maintain its balance, and France would strengthen its energy autonomy. He cites Brazil, where incorporation reaches 32%, or India, which is raising its mandates.
Benjamin Lammert advocates raising "to at least 9%" the 7% ceiling set by the European Union for the contribution of biofuels from food and feed crops to renewable energy targets in transport. In the urgency of the energy crisis linked to the Strait of Hormuz, France has asked the European Commission to raise it to 10%. For the president of the FOP, Europe would benefit doubly. Pressing rapeseed or sunflower seeds yields oil, which can be transformed into biodiesel, but also protein-rich cakes intended for animal feed. Europe imports both fuel and plant proteins, such as soy. Thus, producing more biodiesel would reduce two dependencies at once.
"We must not sacrifice the CAP for the integration of Ukraine." Benjamin Lammert.
Removing European barriers
The challenge now is to convince Brussels. Benjamin Lammert points to the European financial taxonomy, which has classified first-generation biofuels as " brown " activities for the past five years. The result: banks are reluctant to finance new plants. Alexis Patry, on the other hand, sees the redirection as an opportunity to invest in Ukraine, for example in " the rehabilitation of a distillery ", so that " everyone wins ".
However, it is necessary to concretely organize this redirection. Raising incorporation ceilings would create additional outlets for biofuels, without guaranteeing that Ukrainian volumes would be directed there rather than to food markets.
The two officials agree on one point: Ukraine's accession cannot be managed with a fixed framework. " We must not sacrifice the CAP for the integration of Ukraine ", concludes Benjamin Lammert.
Anne Barrat - 26 October 2026
14 October 2026
Anne Barrat - 9 October 2026