Anne BarratPublished on 25 September 2026
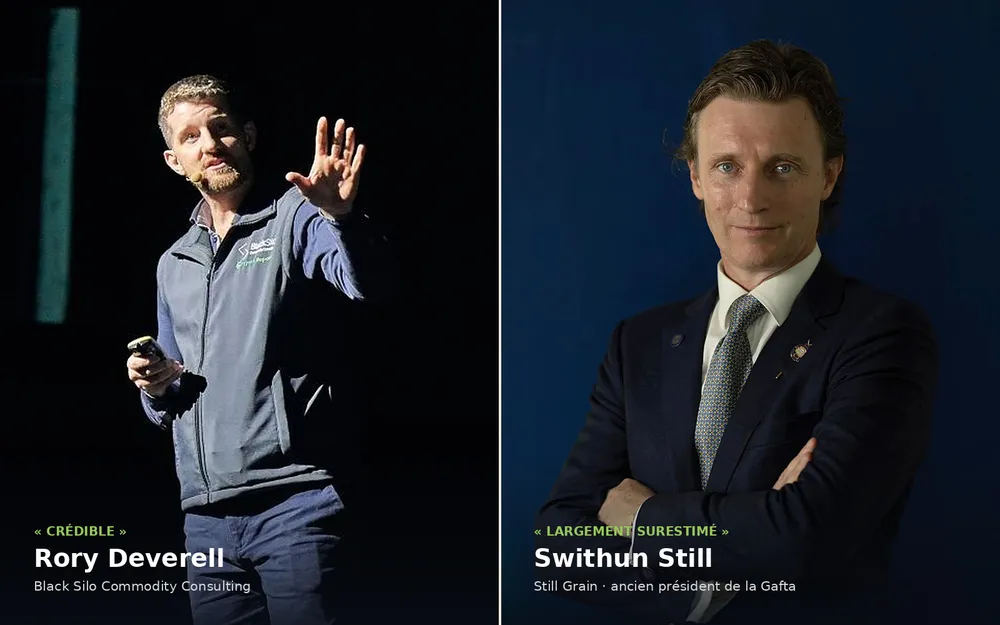
On August 5, 2010, Vladimir Putin announced the closure of Russian wheat exports; ten days later, on August 15, the embargo came into effect and prices soared. On August 4, 2026, a note from Bloomberg revived the same fear: after the strikes on Odessa, Ukrainian agricultural exports could be cut by more than half this season – 29.6 million tons instead of the expected 64.4 – and the country's silos, with a capacity of nearly 59 million tons, could be full by November. Sixteen years later, almost to the day, the market is once again watching for a crash. Two veterans of the Black Sea have agreed to answer the same ten questions: Swithun Still, founder of Solaris and one of the largest exporters of Russian wheat in the world, and Rory Deverell, founder of Black Silo Commodity Consulting. The former responds "largely overestimated." The latter responds "credible."
Bloom Agritech: Many observers are talking about a possible shock in the wheat market. Credible scenario, or largely overestimated?
Swithun Still: Overestimated, and largely so. The risk of a shock exists, but it should not be dramatized. This year's Russian harvest exceeds 92 million tons, according to reliable analysts like SovEcon or IKAR, and stocks are available. Together, Russia (20 to 25% of exported wheat) and Ukraine (5 to 11%) account for nearly 30% of global trade, almost all in the Black Sea. The strikes in the Sea of Azov and the Black Sea are a real logistical shock, but wheat continues to leave: ships are loading every day. The wheat is there, the wheat is moving.
Rory Deverell: Credible, because the disruption is already here. The question is not whether the shock will occur, but how long it will last, and what the supply chain can withstand in the meantime. Alternative routes are about half as efficient as deep-water ports, at a cost two to three times higher.
Does the risk really come from Russian and Ukrainian exports, or, further upstream, from the very capacity of these countries to produce and harvest?
Swithun Still: The real question is the physical availability of wheat, and it is there. The harvest is good: what we are experiencing is a logistics problem, not a production issue. If wheat does not leave at the desired volume now, it will leave later; wheat can be stored for years, provided there are silos, ventilation, and fumigation. Exports can be hindered by so-called secondary sanctions — banks refusing to finance a Russian shipment out of excessive caution — but wheat itself is not sanctioned anywhere. And there is always a bank, in Dubai or elsewhere, willing to make the deal: payment is then settled in dirhams, sometimes in Turkish lira, euros, or even yuan.
Rory Deverell: Today, the grains are there and will be harvested: for the 2026/27 season, it is a matter of logistics, not upstream supply. The real break would rather concern 2027/28, if producers fail to finance and sell their 2026/27 harvest.
If Russia struggled to harvest and export its wheat due to logistical, energy, or financial constraints, what would be the consequences for the global market?
Swithun Still: The scenario seems unlikely to me. The current difficulties in the Sea of Azov will be resolved: Moscow is already subsidizing rail transport to get more wheat out through the Baltic ports, Vysotsk and Ust-Luga. Transporting grain north is not straightforward when it is produced in the south, around Rostov, Krasnodar, or Stavropol, just a few dozen kilometers from the ports, but that is precisely what the subsidies are for.
Rory Deverell: I see no substantial risk. The only point of concern is the sowing of the 2027 harvest. If wheat acreage declines, it will not be because wheat is too expensive to produce, but because rapeseed is more profitable: the rapeseed/wheat price ratio has risen to around 2.3, a level that mechanically encourages sowing oilseeds rather than cereals. This is a cropping decision, not a competitiveness crisis.
What is the biggest risk that grain markets are currently underestimating?
Swithun Still: The market likes risk: without risk, there is no volatility. It is therefore rare for it to underestimate it. The real blind spot is a supply chain that has become too "just-in-time," and countries without a safety net: Ethiopia, Sudan, where unstable states have neither the means nor the storage infrastructure. In contrast, Egypt mandates by law six months of consumption in reserve. I remember August 5, 2010: Putin announced the closure of Russian exports, effective ten days later. Complacency, which consists of thinking "we will always produce enough," is the real danger.
Rory Deverell: The increasing self-sufficiency of importing markets. The Middle East and North Africa harvested a record 94 million tons of small grains this year, including wheat and barley. It is this production that drives import demand, and the market underestimates it.
Could the announced difficulties with corn directly or indirectly heighten tensions over wheat?
Swithun Still: Everything is connected: grains are correlated; when wheat tightens, corn follows, and vice versa. But there is no global problem with corn: the United States and Brazil, now the top producer, dominate; Ukraine remains comfortable, as do Romania, Bulgaria, and Serbia. France has little weight, much less than Ukraine: even if its harvest is cut by 30 to 40%, it remains a non-issue globally. No domino effect on wheat.
Rory Deverell: Possible, but the European Union will compensate for its corn deficit by feeding more wheat and barley to its animals. This is primarily a forage grain issue, distinct from the question of milling wheat from the Black Sea.
Are global stocks sufficient to absorb a simultaneous shock in Russia and Ukraine?
Swithun Still: Yes, but be careful: the global stock figure is misleading, as it is unevenly distributed. China holds a lot, at least according to its official, unverifiable statistics. However, there are indeed stocks in Europe, Russia, and producing countries.
Rory Deverell: Yes. The region in question carries over more than 100 million tons of stocks from the previous campaign, the highest level since 2017.
Beyond prices, what would be the first agricultural and agri-food sectors affected?
Swithun Still: Animal feed manufacturers, bakeries, and especially countries that are structurally dependent on wheat imports, foremost among them those in Africa.
Rory Deverell : The first sector affected is logistics itself. Bringing a ton of wheat from the farm in the Black Sea to the ports of the Red Sea now costs around 275 dollars, compared to 250 a year earlier — and it is maritime freight to the Middle East and North Africa that accounts for most of the increase. Downstream, the consequence is mechanical: the more expensive and complex the chain becomes, the more importing countries have an interest in shortening it, that is, to produce themselves.
Does the situation challenge the food sovereignty strategy of many countries?
Swithun Still : It separates two worlds. Countries that have legislated strategic reserves – Egypt for example, which mandates six months of consumption – are protected. Weaker states, like Ethiopia or Sudan, which lack both the means and the silos, remain exposed. The lesson is not to produce at all costs, but to have stocks.
Rory Deverell : Less than before. Countries in the Middle East and North Africa have gained 35 million tons of wheat and barley production, and are signing a new record this year.
More broadly, has the concentration of global wheat exports among a few major countries become a systemic risk?
Swithun Still : Less than is said. The Black Sea carries weight, but the supply remains diversified: the European Union, Canada, Australia, the United States, and Argentina are all major exporters. When one source closes, another takes over — this is what limits the systemic risk.
Rory Deverell : The last campaign offered the widest range of competing origins in decades. Countries in the Middle East and North Africa are gaining autonomy, Turkey is more often a net exporter than an importer, and India also has an exportable surplus.
If you had to monitor just one indicator in the coming weeks to anticipate the evolution of the wheat market, which one would you choose?
Swithun Still : The volumes actually exported, as tracked by SovEcon among others. One must look at what is actually loaded and shipped from the ports. As long as wheat continues to flow out, the disruption remains logistical; if these flows are interrupted for a long time, the problem changes in nature.
Rory Deverell : The physical market indices from Fryers. When cash follows, or does not follow, the futures markets, it is a directional signal. To measure this, reliable data on the physical market is needed.
Michel J. F. Dubois - 25 September 2026
Anne Barrat - 24 September 2026
Anne Barrat - 4 September 2026